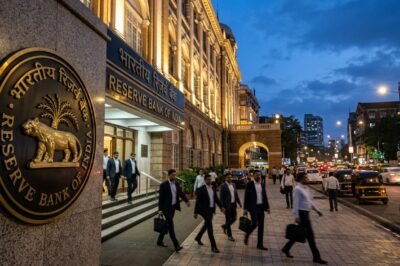
The Mumbai financial corridor is currently weathering a period of significant recalibration as the Indian Rupee dances on the edge of critical psychological levels against a relentlessly strong US dollar. For the Reserve Bank of India (RBI), the task of maintaining currency stability in an era of global volatility has transformed into a high-stakes game of regulatory chess, where every move is scrutinized by global investors and domestic stakeholders alike. However, the latest series of defensive maneuvers—specifically those aimed at curtailing positions in the offshore Non-Deliverable Forward (NDF) markets—has left the commercial banking sector in a state of tactical flux. Sources close to the matter indicate that several major lenders have now formally or informally approached the central bank to seek a more transparent framework. This tension highlights a fundamental struggle within the Indian economy: while the RBI prioritizes macroeconomic stability and the prevention of speculative attacks, commercial banks are grappling with the practicalities of liquidity management, capital requirements, and the fulfillment of legitimate client-driven hedging demands. The call for clarity is not merely an administrative request; it is a plea for a more predictable environment where the market can function without the sudden imposition of informal restrictions that disrupt long-term financial planning.
The Shifting Dynamics of India’s Monetary Guardrails
In the past few months, the Reserve Bank of India has demonstrated an unwavering commitment to preventing the rupee from sliding past key support levels, most notably the 83.00 and 83.50 marks against the dollar. To achieve this, the central bank has employed a multi-pronged strategy that includes direct spot market intervention, management of forward premiums, and, most controversially, administrative nudges to banks. These nudges have reportedly included requests for banks to stop taking arbitrage positions that exploit the price difference between the onshore and offshore rupee markets. While these measures are effective in the short term at squeezing speculators, they often create a vacuum of information for legitimate market participants who rely on these markets for price discovery and risk mitigation.
The current scenario is complicated by the fact that the RBI’s communications are often conducted through informal channels—frequently referred to as “moral suasion” in central banking circles. While this allows the regulator to be nimble, it creates an atmosphere of uncertainty for bank treasuries. Banks have expressed concern that without formal circulars, they are left to interpret the “spirit” of the regulator’s wishes, which can lead to inconsistent compliance across the industry. Furthermore, the lack of a documented policy makes it difficult for banks to explain their reduced market activity to international partners and shareholders who expect a clear regulatory roadmap. The demand for relief is therefore as much about operational certainty as it is about the economic impact of the restrictions themselves.
The Mechanics of Intervention: Spot and Forward Markets
To understand why banks are seeking relief, one must delve into the technicalities of how the RBI defends the rupee. Typically, when the rupee faces depreciation pressure, the RBI sells dollars from its vast foreign exchange reserves in the spot market. However, such interventions drain rupee liquidity from the banking system. To counter this, the RBI often engages in “buy-sell” swaps in the forward market, which helps manage the liquidity impact. Recently, however, the central bank has expanded its toolkit to influence the offshore NDF market, where the rupee is traded outside India’s jurisdiction. By asking domestic banks to limit their participation in these offshore markets, the RBI effectively reduces the supply of rupees available for speculative shorting.
This strategy, while clever, has unintended consequences for the interbank market. Banks rely on the ability to hedge their own currency risks across various jurisdictions. When access to the NDF market is restricted, the cost of hedging increases, and the efficiency of the market declines. Lenders have reported that these restrictions have led to a narrowing of arbitrage opportunities that are essential for market liquidity. Without these mechanisms, the spread between buying and selling rates widens, ultimately increasing the cost of foreign exchange for Indian importers and exporters. This is one of the primary reasons why banks are pushing for a more balanced approach that allows for market-making activities while still protecting the currency from excessive volatility.
Administrative Friction and the Need for Regulatory Easing
The feedback from sources within the banking community suggests that the administrative burden of complying with the RBI’s latest directives is mounting. Banks are not only required to manage their balance sheets but are now also tasked with monitoring their offshore entities’ activities with unprecedented granularity. This heightened surveillance requires significant technological and human resources. Moreover, there is a growing concern that these measures might be perceived as a form of capital control, which could potentially deter foreign institutional investors (FIIs) who prize capital mobility. If global investors feel that the Indian market is becoming too restrictive, the resulting capital outflows could negate the very stability the RBI is trying to preserve.
Furthermore, banks have pointed out that the current restrictions may hamper the development of the GIFT City (Gujarat International Finance Tec-City) as a global financial hub. India has been keen on “onshoring the offshore,” encouraging rupee trading to move from centers like London and Singapore to GIFT City. However, if the RBI continues to impose heavy-handed restrictions on how banks interact with offshore markets, it may discourage international players from setting up shop in India’s new financial gateway. The request for relief is thus a strategic one, aimed at ensuring that the short-term goal of rupee defense does not undermine the long-term objective of financial market liberalization.
Global Macroeconomic Pressures vs. Domestic Stability
The pressure on the rupee is not an isolated phenomenon but a reflection of a broader global trend. The US Federal Reserve’s “higher for longer” interest rate stance has kept the dollar index at elevated levels, drawing capital away from emerging markets toward the safety of US Treasuries. For India, a country that imports a significant portion of its energy needs, a weak rupee translates directly into imported inflation. The RBI is therefore caught between a rock and a hard place: it must allow some depreciation to keep Indian exports competitive, but it must also prevent a freefall that would destabilize the economy. Statistics show that the RBI has spent billions of dollars in reserves over the past year to manage this volatility, a testament to the severity of the challenge.
Despite these challenges, India’s economic fundamentals remain relatively strong compared to its peers. The current account deficit is manageable, and the foreign exchange reserves, while fluctuating, remain substantial. However, the psychological impact of the rupee breaching new lows cannot be understated. It affects corporate sentiment, influences foreign investment decisions, and can even have political ramifications. This environment of heightened sensitivity is exactly why the banking sector is calling for a more transparent dialogue. They argue that if the RBI provides a clearer set of guidelines on what constitutes “allowable” market activity, the banks can better support the regulator’s goals without sacrificing their own operational integrity.
Market Sentiment and the Transparency Gap
Transparency is the bedrock of modern financial markets. When there is a gap between a regulator’s actions and its stated policy, market sentiment can quickly turn from cautious to pessimistic. Currently, the “transparency gap” regarding the rupee defense measures is creating a divergence in how different banks are operating. Larger, more conservative banks might pull back from the market entirely to avoid any potential friction with the regulator, while smaller or more aggressive players might continue to test the limits. This creates an unlevel playing field and reduces the overall depth of the market.
Key Statistics and Market Indicators
- Current Foreign Exchange Reserves: Approximately $600 billion, providing a significant but not infinite buffer.
- Rupee Volatility Index: Has seen spikes during periods of informal RBI intervention.
- Offshore vs. Onshore Spread: Often fluctuates wildly when administrative measures are introduced.
The sources cited in recent reports emphasize that the banks’ request for relief is not an act of rebellion but a request for partnership. In a functioning economy, the central bank and commercial lenders must act in tandem. By providing a clear framework and perhaps easing some of the more stringent informal restrictions, the RBI can foster a healthier market environment. This would allow for more efficient price discovery and ensure that the rupee’s value is a true reflection of economic fundamentals rather than a result of regulatory constraints.
Conclusion: Navigating the Path to a Resilient Rupee
The current standoff between India’s commercial banks and the Reserve Bank of India is a pivotal moment for the country’s financial markets. As the global economic landscape remains fraught with uncertainty—ranging from geopolitical tensions to shifting monetary policies in developed nations—the need for a robust and transparent currency management strategy has never been greater. The RBI’s desire to shield the rupee from speculative volatility is understandable and, in many ways, commendable. However, the methods used must not come at the cost of market efficiency or the international reputation of India’s financial system. Providing the clarity and relief that banks are seeking would not only soothe immediate market jitters but also strengthen the structural integrity of the Indian financial sector.
Ultimately, a resilient rupee is not one that is artificially held at a specific level, but one that can withstand external shocks through a deep, liquid, and well-regulated market. As the dialogue between the banks and the RBI continues, the focus should remain on creating a sustainable framework that balances the need for stability with the requirements of a modern, globalized economy. The coming months will be a true test of India’s monetary diplomacy, as the nation strives to maintain its growth trajectory while navigating the turbulent waters of international finance. Success will depend on the ability of the regulator to listen to the market’s concerns and adapt its strategies to ensure that the rupee remains a symbol of India’s economic strength rather than a point of contention.
Leave a Reply