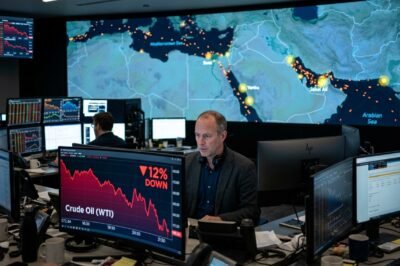
The global energy landscape is currently witnessing a staggering disconnect between traditional geopolitical risk assessments and the hard realities of macroeconomic gravity. In a week that should have seen prices buoyed by escalating maritime threats, crude oil has instead plummeted, heading toward a devastating 12% weekly loss. This precipitous drop comes even as news reports confirm fresh attacks on tankers in the Middle East, a region traditionally considered the heartbeat of global oil supply. For decades, the mere whisper of instability in the Strait of Hormuz or the Red Sea would send Brent and WTI futures skyrocketing; however, the current market psyche appears remarkably insulated from supply-side shocks. Investors are no longer prioritizing the threat of disrupted barrels; instead, they are fixated on a darkening economic horizon characterized by persistent inflation, record-breaking non-OPEC production, and a demand outlook from China that continues to underperform expectations. This 12% slide represents one of the most significant weekly retracements in recent memory, signaling a definitive shift in market sentiment from ‘fear of shortage’ to ‘certainty of surplus.’
The Breakdown of the 12% Weekly Sell-Off
To understand how oil could lose nearly an eighth of its value in just five trading sessions, one must look at the convergence of technical triggers and fundamental weaknesses. The week began with a fragile hope that OPEC+ production cuts would finally tighten the physical market. However, as data points from the United States and Europe began to filter through, it became clear that the ‘higher for longer’ interest rate environment is finally taking its toll on industrial consumption. Crude oil prices today reflect a market that is pricing in a severe manufacturing slowdown. When the 12% drop began, it triggered a wave of programmatic selling as key support levels were breached, turning a controlled descent into a full-scale rout. The liquidation of long positions by hedge funds further accelerated the decline, as traders scrambled to exit bullish bets that were predicated on a geopolitical spike that never materialized in the price action.
Furthermore, the magnitude of this loss is highlighted by the relative silence of the physical market. Despite the headlines of tanker attacks, there has been no actual loss of production. Modern oil markets have become increasingly sophisticated in distinguishing between ‘noise’ and ‘interruption.’ As long as the oil continues to flow—even if the ships carrying it must take longer, more expensive routes around the Cape of Good Hope—the market seems content to treat the geopolitical premium as a secondary concern. This week, the fear of a global recession has proven to be a much more potent driver than the fear of a regional conflict, leading to the aggressive 12% haircut in valuation that has caught many analysts off guard.
The Paradox of Tanker Attacks and Price Inaction
One of the most perplexing aspects of this week’s price action is the failure of fresh tanker attacks to provide a price floor. In a standard market environment, a direct strike on a commercial vessel in a primary shipping lane would trigger an immediate risk premium of $3 to $5 per barrel. Yet, the current reality shows that the market is essentially ‘desensitized’ to these events. This desensitization stems from a belief that the world is currently oversupplied. With the United States reaching record production levels of over 13 million barrels per day, the global cushion is much thicker than it was during the supply shocks of the 1970s or early 2000s. The attacks, while significant for insurance rates and maritime logistics, have not translated into a physical shortage of crude, and in a market dominated by demand-side fears, ‘potential’ disruptions are being ignored in favor of ‘actual’ inventory builds.
Moreover, the logistical shifts in the industry have mitigated the impact of these attacks. Traders have noted that while the Red Sea has become a high-risk zone, the redirection of tankers has become a standardized procedure. The ‘fear factor’ that once drove speculative buying has been replaced by a logistical calculation. Shipowners are paying higher premiums, and delivery times are lengthening, but the oil is still reaching its destination. Consequently, the market sees these attacks as a cost-of-doing-business issue rather than a supply-ending event. This explains why, even as headlines flashed red with reports of maritime skirmishes, the price of WTI and Brent continued their downward trajectory, unfazed by the threat of conflict.
Macroeconomic Headwinds: China and the Federal Reserve
While geopolitics failed to support prices, the twin pillars of global demand—the United States and China—offered plenty of reasons for the sell-off. In China, the world’s largest importer of crude, economic data remains stubbornly lackluster. Refineries in the Asian giant have been cutting run rates as domestic demand for diesel and gasoline struggles to rebound to pre-pandemic growth trajectories. The shift toward electric vehicles (EVs) in China is no longer a fringe factor; it is a structural reality that is permanently eroding the ceiling of oil demand. This structural shift, combined with a property market crisis that shows no signs of resolution, has led to a pessimistic outlook for crude imports for the remainder of the year.
On the other side of the Atlantic, the US Federal Reserve’s stance on interest rates continues to pressure the energy sector. High interest rates bolster the US Dollar, making oil—which is priced in greenbacks—more expensive for international buyers. More importantly, the restrictive monetary policy is designed to cool the economy, which directly correlates to lower fuel consumption. This week, several Fed officials hinted that rate cuts might be further off than the market initially hoped, sparking a renewed wave of selling in the commodities space. The 12% weekly loss is, in many ways, a vote of no confidence in the global economy’s ability to maintain high energy consumption in the face of sustained high borrowing costs.
The Surge in Non-OPEC Supply and the OPEC+ Dilemma
Adding fuel to the bearish fire is the relentless growth of non-OPEC production. The United States, Brazil, and Guyana are pumping oil at record or near-record levels, effectively neutralizing the production cuts implemented by the OPEC+ alliance. This has created a surplus of sweet light crude, particularly in the Atlantic Basin, which has forced prices lower to attract buyers. The 12% drop this week is a signal to OPEC+ that their strategy of price support through supply restriction is facing diminishing returns. The market is essentially daring the cartel to cut further, knowing that doing so would only result in a further loss of market share to American shale producers.
This dynamic has created a ‘price war’ environment, even if it is not explicitly declared. As non-OPEC countries continue to optimize their extraction technologies and bring new projects online, the global supply curve is shifting outward. Investors are looking at the projected supply-demand balance for the next six months and seeing a significant surplus. When you combine a surplus of physical oil with a speculative market that is heavily short, the result is the kind of aggressive double-digit percentage drop we witnessed this week. The 12% loss reflects a realization that OPEC+ may no longer have the leverage required to maintain an $80 or $90 price floor in a world awash with shale oil.
Technical Indicators and Market Sentiment Shifting Bearish
From a technical analysis perspective, the 12% weekly loss has caused significant damage to the long-term charts. Crude oil has broken below its 50-day and 200-day moving averages, a signal that often precedes further weakness. The Relative Strength Index (RSI) has plunged into oversold territory, yet the lack of a ‘dead cat bounce’ suggests that the selling pressure is deeply ingrained. Traders are now looking at previous multi-year lows as the next potential targets. The volume during this week’s sell-off was notably high, indicating that this was not a low-conviction move but a broad-based institutional exit from energy positions.
Sentiment among retail and institutional traders has flipped from ‘buy the dip’ to ‘sell the rip.’ Every minor attempt at a recovery this week was met with aggressive selling, suggesting that the market is looking for a new, lower equilibrium. The psychological impact of losing 12% in a single week cannot be overstated; it shatters the confidence of bulls who believed that geopolitical tensions would provide a permanent safety net. With the volatility index for oil spiking, the cost of hedging has increased, further discouraging participants from taking long positions in a falling market.
Future Implications: What Happens Next?
Looking ahead, the implications of this 12% weekly loss are profound for both producers and consumers. For oil-dependent economies, this drop represents a significant budgetary challenge, potentially leading to reduced government spending or increased borrowing. For the global fight against inflation, however, lower energy prices are a welcome development, as they reduce the cost of transportation and manufacturing across the board. If oil prices remain at these depressed levels, we may see a quicker-than-expected cooling of headline inflation figures, which could ironically give central banks the room they need to finally cut interest rates.
However, the long-term risk remains. Sustained low prices typically lead to a reduction in capital expenditure by oil companies. If investment in new production stalls because prices are too low to justify the risk, we could be setting the stage for a massive supply crunch three to five years down the line. For now, the market is living in the present, and the present is defined by an abundance of oil and a scarcity of economic optimism. The coming weeks will be critical as the market attempts to find a floor. Will the tanker attacks eventually spark a rally, or is the 12% loss just the beginning of a larger structural decline? Only the data from the upcoming refinery maintenance season and the next round of central bank meetings will provide the answer. For today, the bears are firmly in control of the oil pits.
Leave a Reply