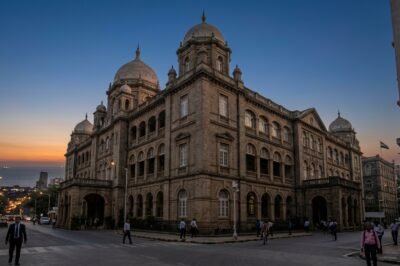
The Reserve Bank of India (RBI) has escalated its legal battle over the restructuring of Yes Bank by filing a review petition against the Supreme Court’s directives concerning the write-off of Additional Tier-1 (AT-1) bonds. This move marks a critical juncture in the history of Indian financial regulation, highlighting a profound tension between the central bank’s mandate to maintain financial stability and the judiciary’s role in protecting contractual and investor rights. When the RBI stepped in to rescue Yes Bank in March 2020, it acted with unprecedented speed to prevent a systemic collapse that threatened to destabilize the entire Indian private banking sector. At the heart of this rescue was the controversial decision to completely write off Rs 8,415 crore worth of AT-1 bonds, effectively wiping out the investments of thousands of retail and institutional players. The RBI argues that these bonds are designed to be loss-absorbent, acting as a buffer that must be exhausted before depositors face any risk. However, the subsequent legal challenges have raised fundamental questions about the transparency of the process and the procedural legality of how these decisions were executed under the Yes Bank Reconstruction Scheme 2020.
The move to seek a review is not merely about the specific case of Yes Bank; it is a strategic effort by the RBI to preserve its ‘resolution toolkit.’ If the central bank cannot reliably write down high-risk capital instruments during a crisis, the cost of emergency interventions could become prohibitively high, potentially forcing the government to use taxpayer money for future bailouts. This legal saga has already seen the Bombay High Court ruling in favor of the bondholders, citing procedural lapses, which the RBI now seeks to address at the highest judicial level. The outcome of this petition will set a precedent for how future bank failures are handled in India, determining whether the ‘rules of the game’ for high-yield banking instruments are set by the regulator’s immediate survival needs or by the strict letter of contractual law. As the financial community watches closely, the stakes involve not just billions of rupees, but the very credibility of India’s banking regulatory framework in the eyes of global investors.
The Genesis of the Crisis: Why Yes Bank’s AT-1 Bonds Were Wiped Out
To understand the current legal friction, one must look back at the state of Yes Bank in early 2020. The bank was suffering from a massive surge in non-performing assets (NPAs) and a rapid depletion of its capital buffers. As a ‘too big to fail’ institution, its collapse would have triggered a domino effect across the Indian economy. Under the Basel III framework, AT-1 bonds are perpetual debt instruments that qualify as quasi-equity because they contain a ‘loss-absorption’ clause. This clause allows the issuer to write down the bonds or convert them into equity if the bank’s Common Equity Tier 1 (CET1) ratio falls below a specific trigger point, or if the regulator deems the bank to have reached the ‘Point of Non-Viability’ (PONV).
On March 14, 2020, as part of the State Bank of India-led reconstruction plan, the RBI-appointed administrator exercised this power. The bonds were written off entirely. For the RBI, this was a textbook application of global banking norms intended to protect the bank’s viability. For the investors, however, it was a breach of trust. Many retail investors alleged that they were ‘mis-sold’ these bonds as safe, high-interest alternatives to fixed deposits, without adequate disclosure of the fact that their entire principal could be erased. This discrepancy between the technical nature of the instrument and the marketing practices of the bank created the emotional and legal ground for the ensuing four-year battle.
The Judicial Journey: From the Bombay High Court to the Supreme Court
The legal battle gained significant momentum in January 2023 when the Bombay High Court delivered a landmark judgment. The court quashed the RBI administrator’s decision to write off the AT-1 bonds, primarily on procedural grounds. The court observed that the write-off occurred after the final reconstruction scheme had been notified, arguing that the administrator no longer possessed the specific powers required to cancel the bonds at that stage. This ruling was a massive victory for the bondholders and a significant setback for the RBI, as it suggested that the regulator’s emergency powers are not absolute and must follow a precise chronological order.
The RBI and the Union government quickly appealed to the Supreme Court, which initially stayed the High Court’s order but has since made observations that led to the current review petition. The central bank is now arguing that the High Court’s interpretation creates a dangerous legal vacuum. If a regulator cannot act between the announcement of a moratorium and the final implementation of a rescue plan, it loses the agility needed to stop a bank run. The RBI’s review petition seeks to clarify that the determination of ‘Non-Viability’ is a regulatory judgment that should not be constrained by the hyper-technical timing of when the final notification is published.
The RBI’s Arguments: Systemic Stability vs. Procedural Technicalities
In its review petition, the RBI is expected to emphasize that AT-1 bonds are essentially ‘risk capital.’ Unlike depositors who are the primary concern of the regulator, AT-1 bondholders are investors who accept higher interest rates in exchange for the risk of loss during a crisis. The RBI maintains that the ‘regulatory hierarchy’ must be respected: first, equity shareholders lose money, then AT-1 bondholders, and only then do depositors or senior creditors face haircuts. By challenging the Supreme Court’s stance, the RBI is trying to prevent a scenario where bondholders are treated as ‘higher priority’ than the institution’s own survival.
Furthermore, the RBI argues that if the write-off is reversed, Yes Bank—which has since returned to profitability and stability—would face a sudden liability of over Rs 8,400 crore plus interest. This could jeopardize the bank’s current recovery and necessitate another round of capital infusion, potentially involving public funds. The RBI’s stance is that the court must look at the ‘macro-prudential’ necessity of the write-off rather than focusing solely on the ‘micro-procedural’ steps taken during a weekend of financial chaos where the objective was to save millions of depositors.
Market Statistics and the Cost of Capital for Indian Banks
The market impact of the Yes Bank AT-1 bond saga has been profound. Following the 2020 write-off, the spread on AT-1 bonds issued by other private banks widened significantly. Investors began demanding a ‘risk premium’ for these instruments, making it more expensive for banks to raise capital. According to market data, the yield on AT-1 bonds from mid-tier private banks jumped by 100-200 basis points in the immediate aftermath of the crisis. If the RBI fails to secure a favorable review, the uncertainty surrounding the ‘enforceability’ of write-down clauses could lead to a permanent increase in the cost of capital for the Indian banking sector.
- Total AT-1 Write-off: Rs 8,415 crore.
- Impacted Investors: Over 13,000 retail investors and several large mutual funds.
- Market Spread: Increased by an average of 1.5% for similar instruments post-2020.
- Current Outstanding AT-1 Bonds: Indian banks have over Rs 1 lakh crore in outstanding AT-1 bonds that rely on these regulatory definitions.
The RBI is concerned that a legal precedent favoring bondholders will make Indian AT-1 bonds ‘non-compliant’ with Basel III standards in the eyes of international rating agencies. This could lead to a downgrade of the standalone credit profiles of Indian banks, further increasing borrowing costs on a global scale. Therefore, the review petition is also a move to ensure that India remains aligned with international financial standards.
Investor Sentiment and the Mis-selling Narrative
While the RBI focuses on the technicalities of the Banking Regulation Act, the human element of this story cannot be ignored. The ‘mis-selling’ aspect remains the strongest moral argument for the bondholders. Investigations have shown that many investors were told these bonds were ‘as safe as FDs.’ In response, SEBI (the Securities and Exchange Board of India) has already implemented stricter rules, including raising the minimum investment size for AT-1 bonds to Rs 1 crore to effectively bar retail participation. However, these rules do not help those who already lost their money in the Yes Bank collapse.
The review petition will likely trigger another wave of anxiety among the original bondholders who have been waiting for years for a final resolution. For them, the RBI’s move is seen as an attempt to deny them the relief granted by the High Court. The Supreme Court will have the difficult task of balancing the ‘law of contracts’ and the ‘doctrine of necessity.’ If the court finds that the mis-selling was widespread, it may look for a middle ground—perhaps a partial conversion of bonds into equity—though the RBI has historically resisted such compromises during a resolution process.
Conclusion: Future Implications for Financial Governance
The RBI’s decision to seek a review of the Supreme Court’s order is a defining moment for the future of Indian banking. The outcome will determine the extent of the central bank’s discretionary powers and the level of protection afforded to high-risk investors. If the RBI succeeds, it will solidify a regulatory regime where ‘financial stability’ is the supreme law, providing the regulator with the absolute authority to reconfigure a bank’s capital structure in times of distress. This would offer long-term clarity to the market but would also serve as a stark reminder of the ‘caveat emptor’ principle for investors chasing high yields.
Conversely, if the petition is dismissed, it will signal a shift toward greater judicial oversight of regulatory decisions. The RBI would be forced to adopt more rigid and perhaps slower resolution processes, which could be risky in an era of digital bank runs. It would also necessitate a complete redesign of Tier-1 capital instruments in India to ensure they are legally ‘bulletproof’ against future challenges. As the apex court takes up the review, the banking industry stands at a crossroads, awaiting a verdict that will shape the risk appetite and capital architecture of the Indian economy for the next generation.


Leave a Reply