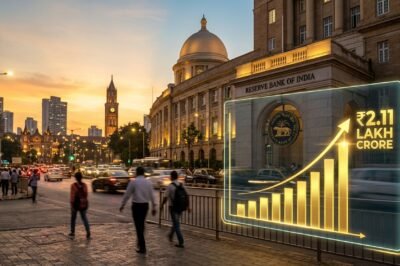
The Indian financial landscape witnessed a seismic shift as the Reserve Bank of India (RBI) announced an unprecedented surplus transfer of ₹2.11 lakh crore to the Union Government for the fiscal year 2023-24. This monumental payout, sanctioned during the 604th meeting of the Central Board of Directors chaired by Governor Shaktikanta Das, represents a staggering increase of approximately 141 percent compared to the previous year’s transfer of ₹87,416 crore. In an era where global economies are grappling with fiscal volatility and inflationary pressures, this massive dividend serves as a vital economic cushion for the Indian administration. The announcement significantly outperformed both market expectations and the government’s own budgetary estimates, which had conservatively projected a dividend of roughly ₹1.02 lakh crore from the central bank and public sector financial institutions combined. This fiscal windfall arrives at a critical juncture, providing the government with enhanced flexibility to manage its fiscal deficit, accelerate capital expenditure, and potentially navigate the complexities of global economic headwinds with greater resilience.
The Anatomy of a Record-Breaking Surplus
The record surplus is not merely a statistical anomaly but a reflection of the RBI’s strategic financial management over the past fiscal year. Primary drivers behind this massive income include the significant interest earned on foreign exchange reserves and the gains from the central bank’s foreign exchange interventions. As the RBI managed the volatility of the Indian Rupee against the US Dollar, it engaged in substantial buy-sell operations that yielded high returns. Additionally, the rising interest rates in developed markets, particularly in the United States, meant that the RBI’s investments in foreign sovereign securities, such as US Treasury bills, fetched much higher yields than in previous cycles. This external income was complemented by internal revenue streams, including interest on rupee-denominated government securities held under Open Market Operations (OMO).
Furthermore, the RBI’s balance sheet expansion and the effective management of liquidity within the domestic banking system played a pivotal role. While the central bank absorbed excess liquidity through various windows, the cost of these operations was managed against the backdrop of robust domestic credit growth. The sheer scale of the ₹2.11 lakh crore transfer underscores the profitability of the central bank’s core functions during a period of high global interest rates and active currency management. It is important to note that this surplus is calculated after ensuring that the RBI maintains its necessary capital requirements and risk provisions, ensuring that the central bank’s own financial health remains beyond reproach.
The Contingency Risk Buffer: Balancing Growth and Stability
A crucial aspect of the board’s decision was the adjustment of the Contingency Risk Buffer (CRB). Following the recommendations of the Bimal Jalan Committee, the RBI is required to maintain a CRB within the range of 5.5 percent to 6.5 percent of its balance sheet. For the fiscal year 2023-24, the board decided to increase the CRB to the upper limit of 6.5 percent, up from 6.0 percent in the previous year. This decision highlights a prudent approach to central banking, prioritizing financial stability in an increasingly uncertain global environment. By shoring up its reserves to the maximum recommended level, the RBI has ensured it has enough ammunition to handle potential shocks, such as extreme currency volatility or systemic liquidity crises.
The increase in the CRB to 6.5 percent makes the ₹2.11 lakh crore payout even more impressive. Had the board decided to keep the buffer at the lower end of 5.5 percent, the surplus transfer could have been even larger. This choice reflects the maturity of India’s monetary authority, which seeks to support the government’s fiscal goals without compromising its own long-term institutional strength. Analysts suggest that the decision to stick to the upper bound of the CRB was a signal to international rating agencies and global markets that India remains committed to conservative and stable financial practices, even when presented with the opportunity for even larger short-term payouts.
Fiscal Deficit Implications and Budgetary Relief
The most immediate and profound impact of this transfer will be felt in the government’s fiscal deficit management. For the financial year 2024-25, the government has set a target to bring the fiscal deficit down to 5.1 percent of the Gross Domestic Product (GDP). With this dividend being nearly ₹1.1 lakh crore higher than the initial budget estimate, the government now finds itself with an additional 0.3 percent to 0.4 percent of GDP in revenue. This provides a significant buffer that can be used in several ways: it can be utilized to reduce the fiscal deficit even further than the 5.1 percent target, or it can be deployed to increase government spending on infrastructure and social schemes without increasing the borrowing program.
Most economists believe the government will use this windfall to adhere strictly to its fiscal consolidation roadmap while potentially ramping up capital expenditure (Capex). High Capex has been a cornerstone of the current administration’s economic policy, aimed at driving long-term growth through the creation of assets like roads, railways, and digital infrastructure. The extra funds from the RBI mean the government can sustain this momentum without putting additional pressure on the bond markets. This is particularly relevant as India aims to reduce its debt-to-GDP ratio, which had climbed during the pandemic years. The surplus acts as a non-tax revenue boost that strengthens the sovereign credit profile of the country.
Impact on the Debt Market and Interest Rates
The announcement had an immediate cooling effect on the Indian bond market. Government securities (G-Sec) yields softened as investors anticipated that the government might reduce its market borrowing for the second half of the fiscal year. Lower yields translate to lower borrowing costs for the government and, eventually, for the corporate sector. When the government needs to borrow less from the market, it leaves more room for private sector credit, reducing the ‘crowding out’ effect. This is essential for stimulating private investment, which has been showing signs of recovery but requires a stable interest rate environment to fully take off.
Furthermore, the infusion of this surplus into the government’s accounts will eventually lead to an increase in systemic liquidity. When the government spends this money, it flows back into the banking system, which could help ease the liquidity deficit that has plagued Indian banks for several months. Improved liquidity can lead to more stable short-term interest rates and could potentially influence the RBI’s future monetary policy decisions. While the RBI remains focused on bringing inflation down to its 4 percent target, the improved fiscal position of the government provides the central bank with more breathing room to manage the liquidity-growth-inflation trilemma without needing to resort to aggressive market interventions.
Comparative Historical Analysis
To understand the magnitude of this year’s transfer, one must look at the historical data. In FY19, the RBI transferred ₹1.76 lakh crore, which was previously the highest ever, following the acceptance of the Bimal Jalan Committee’s framework. In subsequent years, the transfers were significantly lower, such as ₹30,307 crore in FY22 and ₹87,416 crore in FY23. The jump to ₹2.11 lakh crore in FY24 is a testament to the unique convergence of high global interest rates and efficient domestic management. It marks a transition from a period of moderate transfers to a ‘high-surplus’ era, driven largely by the RBI’s massive foreign exchange reserve of over $640 billion, which generates substantial earnings in a high-yield global environment.
Market Sentiment and Global Perspectives
Global investors and credit rating agencies are likely to view this development positively. A higher-than-expected dividend strengthens the government’s balance sheet and demonstrates the profitability of the central bank, which is often seen as a proxy for the country’s overall economic health. It reinforces the narrative of India as a ‘bright spot’ in the global economy. By using these funds to lower the fiscal deficit, India can improve its chances of a sovereign rating upgrade, which would further lower the cost of capital for Indian companies looking to raise debt internationally. The stock markets also reacted with optimism, as the financial sector stands to benefit from improved liquidity and the prospect of lower bond yields.
Conclusion: Future Implications and Economic Outlook
The RBI’s record surplus transfer of ₹2.11 lakh crore is a watershed moment for India’s fiscal policy in FY24. It provides the central government with an unexpected but highly welcome financial cushion that can be used to consolidate the fiscal deficit, boost infrastructure spending, and maintain economic stability during a period of global uncertainty. While the windfall is significant, the RBI’s decision to simultaneously increase the Contingency Risk Buffer to 6.5 percent ensures that this payout does not come at the expense of institutional safety. Moving forward, the focus will shift to how the Ministry of Finance allocates these funds in the upcoming full budget. Whether the government chooses to accelerate debt reduction or fuel further capital projects, the underlying reality is that the Indian economy now possesses enhanced fiscal space to pursue its growth ambitions. This surplus transfer not only stabilizes the current fiscal year but also sets a positive tone for India’s journey toward becoming a $5 trillion economy, signaling robust health within its primary monetary institution and a collaborative approach toward national fiscal management.
Leave a Reply