Introduction: A New Era of Growth for the Mountain View Giant
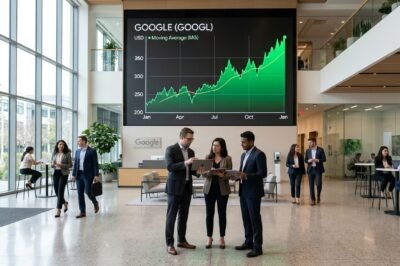
In a landscape increasingly defined by the competitive arms race of generative artificial intelligence and high-scale cloud infrastructure, Alphabet Inc. has once again asserted its dominance. The third-quarter earnings report released by the parent company of Google has not only surpassed conservative analyst estimates but has shattered expectations across several key performance indicators. Investors reacted with immediate fervor, sending shares surging in after-hours trading as the company proved that its heavy investments in AI are finally translating into significant top-line and bottom-line growth. This quarter marks a pivotal moment for Alphabet, as it successfully navigated the transition from a search-first to an AI-first organization, while simultaneously scaling its cloud division into a profit-generating powerhouse that can no longer be viewed as a mere secondary segment to its advertising business.
The centerpiece of this earnings beat was undoubtedly Google Cloud, which saw an acceleration in growth that caught many on Wall Street by surprise. As enterprises globally shift their workloads to the cloud to take advantage of machine learning and large language models, Alphabet has positioned itself as the infrastructure of choice. This success is not just a reflection of market demand but a testament to the strategic integration of Gemini, Alphabet’s proprietary AI model, across its entire ecosystem. From YouTube’s monetization strategies to the efficiency of Google Search, the impact of AI is ubiquitous. In the following analysis, we will dive deep into the specific financial metrics, the strategic shifts within the cloud business, and what this means for the broader technology sector as we head into the final quarter of the year.
The Google Cloud Phenomenon: From Infrastructure to Innovation Hub
For years, Google Cloud was often criticized for being a distant third to Amazon Web Services and Microsoft Azure. However, the Q3 results tell a story of rapid convergence. Google Cloud revenue surged by 35% year-over-year, reaching a staggering $11.35 billion. This exceeds the growth rates seen in previous quarters and highlights a significant shift in enterprise preference. The operating income for the cloud division also saw a dramatic improvement, proving that the segment has achieved the necessary scale to sustain high margins. This profitability is crucial because it allows Alphabet to reinvest in the very data centers and custom silicon, like the Tensor Processing Units (TPUs), that fuel its AI capabilities.
The growth in cloud isn’t just about storage or basic computing power; it is deeply rooted in the demand for AI services. Alphabet CEO Sundar Pichai noted during the earnings call that the company’s full-stack AI approach is a major differentiator. Organizations are choosing Google Cloud because it offers the best environment to train and deploy complex models. Furthermore, the integration of Gemini into Google Workspace has led to increased average revenue per user, as businesses are willing to pay a premium for AI-driven productivity tools. This synergy between infrastructure and software-as-a-service (SaaS) is a powerful engine for Alphabet’s future valuation.
Advertising Resilience Amidst Economic Uncertainty
While Cloud stole the headlines, Alphabet’s core advertising business showed remarkable resilience. Google Search and other related revenues grew to $49.4 billion, a 12% increase that demonstrates the enduring power of intent-based marketing. Despite concerns that AI-powered search engines might cannibalize traditional search traffic, Alphabet’s rollout of AI Overviews has actually increased user engagement in certain demographics. Users are finding that the summarized results provide quicker answers to complex queries, leading to more frequent usage of the platform. This suggests that Alphabet is successfully evolving its search product without alienating its massive advertiser base.
YouTube also contributed significantly to the beat, with advertising revenue rising to $8.92 billion. The growth of YouTube Shorts has been a particular bright spot, as the platform continues to compete effectively against TikTok for the attention of Gen Z and millennial audiences. Monetization of Shorts is improving as Alphabet refines its algorithmic ad placement, ensuring that creators remain incentivized to produce high-quality short-form content. Additionally, the subscriptions business, including YouTube TV and YouTube Music, has crossed significant milestones, providing a stable stream of recurring revenue that balances the cyclical nature of ad spending.
Capital Expenditure and the Cost of AI Leadership
Maintaining a lead in the AI race comes with a high price tag, and Alphabet’s capital expenditure (CapEx) for the quarter reflects this reality. The company reported $13 billion in CapEx, primarily directed toward servers and data centers. While some investors have expressed concern about the long-term return on these investments, Alphabet’s management has been clear: the risk of under-investing in AI is far greater than the risk of over-investing. These investments are the foundational bedrock for the next decade of digital services. By building out its own infrastructure and designing its own chips, Alphabet is reducing its reliance on third-party hardware providers and lowering its long-term operational costs.
Furthermore, Alphabet has shown a renewed commitment to cost discipline in other areas. The company’s headcount has been managed more strictly than in the previous decade, and there is a concerted effort to use AI internally to streamline coding and administrative tasks. This focus on efficiency has allowed operating margins to expand to 32%, a significant achievement given the inflationary pressures and the high costs of specialized talent in the tech industry. The balance between aggressive investment in the future and disciplined management of the present is what makes Alphabet’s current financial position so robust.
Competitive Positioning Against Azure and AWS
In the broader context of the ‘Cloud Wars,’ Alphabet is gaining ground. While Microsoft and Amazon still command larger market shares, Google Cloud’s growth rate is now outpacing its rivals in several key segments. One of the primary drivers is the open nature of Google Cloud’s ecosystem, which allows developers to integrate various AI models more easily than in more closed environments. Alphabet’s focus on multi-cloud and hybrid-cloud solutions has also resonated with large enterprises that are wary of vendor lock-in. This strategic flexibility is attracting a diverse range of clients, from traditional financial institutions to cutting-edge biotech firms.
The competitive landscape is also being reshaped by the hardware layer. Alphabet’s 6th generation of TPUs provides a performance-per-dollar advantage for specific AI training tasks that is difficult for competitors using off-the-shelf hardware to match. As the industry moves toward more specialized AI applications, this vertical integration from silicon to software will be a critical advantage. Analysts are increasingly seeing Alphabet not just as a search company, but as the premier AI infrastructure provider, a shift in perception that is likely to support a higher price-to-earnings multiple in the long term.
Market Reaction and Analyst Perspectives
The market’s reaction was swift and overwhelmingly positive. Alphabet’s stock price jumped over 5% in the minutes following the release, reflecting a collective sigh of relief from investors who were worried about a potential slowdown in digital advertising. Wall Street analysts have been quick to revise their price targets upward, citing the strength of the Cloud division as a primary catalyst. Many now believe that the narrative surrounding Alphabet has fundamentally changed; it is no longer a defensive play in search, but an offensive play in the next generation of computing.
Several top-tier investment firms have highlighted the ‘Gemini effect’ as a key driver for future growth. By integrating its most advanced AI models into its most popular products, Alphabet is creating a virtuous cycle where data improves the models, which in turn improves the user experience, leading to more data. This feedback loop is a moat that is incredibly difficult for startups or even well-funded competitors to breach. The consensus among the financial community is that Alphabet has successfully navigated the ‘innovator’s dilemma,’ disrupting its own core business with AI before others could do it for them.
Conclusion: The Future Outlook for Alphabet
Looking ahead, the trajectory for Alphabet remains decidedly bullish. The company’s ability to generate massive amounts of free cash flow allows it to fund the expensive transition to AI without sacrificing its financial stability. As Google Cloud continues to scale toward $50 billion in annual revenue, it will become an even more significant contributor to the company’s overall valuation. The integration of AI into Search and YouTube is still in its early innings, with significant untapped potential in personal assistant features and automated video creation. Alphabet is not just surviving the AI revolution; it is architecting it.
However, challenges remain. Regulatory scrutiny continues to be a persistent shadow over the company, with antitrust lawsuits in both the US and Europe potentially threatening its dominant market position. Additionally, the cost of AI infrastructure will require Alphabet to maintain its high level of operational efficiency to keep margins from eroding. Nevertheless, based on the Q3 performance, Alphabet has proven it has the strategic vision and the execution capability to overcome these hurdles. For investors and industry observers alike, the message from this quarter is clear: Google is back on the offensive, and its cloud-fueled growth is just the beginning of a new chapter in the company’s storied history.
Leave a Reply