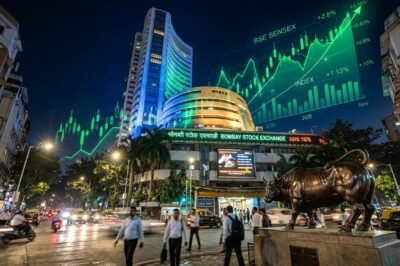
The Indian financial landscape witnessed a historic milestone as the benchmark equity indices, the S&P BSE Sensex and the NSE Nifty 50, surged to unprecedented record highs, driven by a wave of euphoria following a landmark announcement from the Reserve Bank of India (RBI). The central bank’s board approved a record-breaking surplus transfer of ₹2.11 lakh crore to the Union Government for the fiscal year 2023-24, a figure that nearly doubled the initial budgetary estimates and surpassed the most optimistic projections of market analysts. This financial windfall has fundamentally altered the sentiment on Dalal Street, providing a significant boost to the government’s fiscal position and fueling expectations of accelerated capital expenditure or a faster-than-anticipated reduction in the fiscal deficit. As trading commenced after the news, investor confidence was palpable, with large-cap stocks across the banking, infrastructure, and energy sectors seeing massive buy-side interest. The record-breaking rally reflects the market’s belief in India’s robust macroeconomic fundamentals and the central bank’s prudent management of its balance sheet. This surge not only highlights the resilience of the domestic economy amidst global uncertainties but also positions India as a standout performer in the emerging markets space, attracting both domestic and foreign institutional investors to participate in this momentum-driven bull run.
The Unprecedented Dividend: A Fiscal Catalyst for Markets
The Reserve Bank of India’s decision to transfer a surplus of ₹2.11 trillion (₹2,10,874 crore) to the central government is nothing short of a fiscal game-changer. For context, the government had estimated a dividend of approximately ₹1.02 lakh crore from the RBI and public sector financial institutions combined in the interim budget. This massive surplus, which is roughly 141 percent higher than the ₹87,416 crore transferred in the previous fiscal year, provides the government with an additional fiscal space of approximately 0.3 to 0.4 percent of the GDP. This unexpected revenue stream is a direct result of higher interest income from both domestic and foreign assets, along with significant gains from the RBI’s foreign exchange interventions over the last year.
Economists and market strategists believe that this windfall will provide the government with several strategic options. Firstly, it could be used to narrow the fiscal deficit target for FY25 from the current projection of 5.1 percent to potentially below 5 percent, which would be a significant signal of fiscal discipline to global rating agencies. Alternatively, the government could choose to increase its allocation for capital expenditure, which has been the primary engine of India’s economic growth in the post-pandemic era. Increased public spending on infrastructure, roads, and railways would have a multiplier effect on the economy, further supporting the corporate earnings growth that investors are currently pricing into the stock market.
The impact on the bond market was equally pronounced, as the news led to a sharp cooling of sovereign bond yields. Lower yields typically translate to lower borrowing costs for corporations, which in turn boosts profitability and stock valuations. The 10-year benchmark bond yield saw a notable decline, reflecting the market’s appreciation of the reduced borrowing pressure on the government. This synergy between the fiscal boost and the monetary environment has created a perfect storm for the equity markets to scale new heights, as the risk premium for Indian equities appears to be shrinking in the eyes of institutional players.
Record Highs on Dalal Street: Sensex and Nifty at the Pinnacle
Following the news, the BSE Sensex crossed several psychological resistance levels, reaching an all-time intraday high that left market participants in awe. The Nifty 50 followed suit, breaching the significant 22,900 and 23,000 marks with relative ease. The breadth of the market was exceptionally positive, with the number of advancing stocks far outnumbering the decliners. This broad-based rally was not just confined to the front-line indices; mid-cap and small-cap stocks also witnessed renewed interest as the overall risk appetite of the market expanded. The India VIX, a measure of market volatility and fear, saw a significant cooling off, indicating that the immediate anxiety surrounding political developments and global rate paths had been temporarily eclipsed by the positive domestic news flow.
Technical analysts pointed out that the breakout was accompanied by strong volumes, a classic indicator of a sustainable trend. The Nifty 50 has now established a new base at higher levels, with previous resistance zones now acting as firm support. Market veterans observed that the rally was characterized by ‘quality buying,’ where institutional investors were seen accumulating shares in fundamentally strong companies rather than speculative plays. This suggests that the current record highs are backed by a genuine improvement in the macro-outlook rather than just technical momentum. The psychological impact of hitting record highs cannot be overstated, as it often triggers a ‘fear of missing out’ (FOMO) among retail investors, further driving liquidity into the markets.
The performance of the banking sector was particularly noteworthy. The Nifty Bank index outperformed the broader market, as the dividend news specifically benefits the public sector banks through improved sentiment around government finances. Large-cap private banks also participated in the rally, as the overall liquidity environment is expected to remain favorable. The heavyweights like HDFC Bank, Reliance Industries, and ICICI Bank provided the necessary heavy lifting to push the indices into uncharted territory. As the market digests these gains, the focus is shifting toward the sustainability of these levels in the face of upcoming quarterly earnings and the final results of the general elections.
Banking and Financial Services: The Engine of Growth
The banking sector has been the primary beneficiary of the RBI’s dividend announcement, and for good reason. As the largest component of the Nifty 50, the performance of banks often dictates the direction of the entire market. The surge in bank stocks was driven by the realization that a stronger government fiscal position reduces the pressure on the banking system to fund public sector projects. Furthermore, the record dividend reflects the high profitability of the RBI’s operations, which is often a proxy for the health of the broader financial ecosystem. Public sector banks (PSBs) saw their shares jump significantly, as investors anticipate that the government might use part of the windfall to further strengthen the capital base of these institutions or to reduce its market borrowing, which keeps liquidity in the system.
Beyond the immediate fiscal impact, the banking sector is also benefiting from robust credit growth and improving asset quality. The latest data suggests that bank credit is growing at a healthy double-digit pace, fueled by demand from the retail, housing, and corporate sectors. The cleaning up of bank balance sheets over the last few years has resulted in multi-year low non-performing asset (NPA) ratios, making the sector highly attractive to value investors. When combined with the RBI’s dividend-induced optimism, the banking sector has become the ‘safety trade’ for many institutional portfolios. This is evident in the massive inflows into banking ETFs and mutual funds over the past few sessions.
The financial services sector, including Non-Banking Financial Companies (NBFCs) and insurance firms, also joined the rally. The expectation of a stable interest rate environment, supported by the RBI’s comfortable fiscal cushion, is a positive for these entities. Lower bond yields help NBFCs lower their cost of funds, improving their net interest margins. Insurance companies, which are large holders of government securities, benefit from the appreciation in the value of their bond portfolios as yields drop. The entire financial stack is currently witnessing a re-rating, as the market begins to factor in a period of sustained profitability and low systemic risk.
Macroeconomic Implications: Reducing Fiscal Deficit Pressures
The dividend transfer of ₹2.11 lakh crore is equivalent to approximately 0.6% of the budgeted GDP for the current year. This is a massive injection that gives the Ministry of Finance significant leverage. One of the most immediate implications is the potential for the government to achieve its fiscal deficit target of 5.1% of GDP with much greater ease. In fact, many analysts are now projecting that the fiscal deficit could end up being closer to 4.8% or 4.9% if the government maintains its current spending discipline. Such a reduction would be viewed very favorably by international rating agencies like S&P, Moody’s, and Fitch, which have been closely monitoring India’s debt-to-GDP ratio and fiscal trajectory.
Furthermore, the extra funds reduce the government’s need to issue fresh debt in the market. A reduction in the gross market borrowing program for the second half of the fiscal year is now a distinct possibility. When the government borrows less, more capital is available for the private sector, which helps keep interest rates in check. This ‘crowding in’ of private investment is essential for India to reach its long-term goal of becoming a $5 trillion economy. The market rally is essentially a celebration of this virtuous cycle where fiscal strength leads to lower rates, higher investment, and ultimately, higher corporate earnings.
Another macroeconomic benefit is the impact on inflation management. With a strong fiscal cushion, the government is less likely to resort to inflationary measures to fund its expenditures. The RBI also gains more flexibility in its monetary policy. While the central bank remains committed to bringing inflation down to its 4% target, the fiscal windfall reduces the burden on monetary policy to be the sole stabilizer of the economy. This coordination between the North Block and Mint Street has been a hallmark of India’s recent economic policy, and the record dividend is the latest evidence of this successful partnership. Investors are betting that this stability will lead to a more predictable and investor-friendly environment in the years to come.
Institutional Investor Behavior: FIIs vs. DIIs
The record highs have also brought the spotlight back onto the behavior of Foreign Institutional Investors (FIIs) and Domestic Institutional Investors (DIIs). In the months leading up to this rally, FIIs had been somewhat cautious, often acting as net sellers due to rising US Treasury yields and geopolitical tensions in the Middle East. However, the RBI dividend news seems to have acted as a turning point. The sheer scale of the fiscal boost makes the Indian story too compelling to ignore, even for the most skeptical global fund managers. We are seeing a gradual return of foreign capital into Indian equities, as the growth-inflation dynamics in India look far superior to those in other emerging or developed markets.
On the other hand, Domestic Institutional Investors, led by mutual funds and insurance companies, have been the bedrock of the Indian market for several years. Their consistent buying, supported by the steady flow of Systematic Investment Plans (SIPs) from retail investors, has provided a cushion against FII outflows. The current record highs are a validation of the ‘India Inside’ strategy followed by many domestic fund managers. With the RBI dividend adding a new layer of fundamental support, DIIs are likely to remain bullish, further deepening the domestic equity culture. The interplay between returning FII liquidity and resilient DII support is providing the necessary ‘fuel’ for the indices to sustain their upward trajectory.
Market analysts also point out that the global context is shifting. As the US Federal Reserve prepares for an eventual pivot in interest rates, the ‘carry trade’ is becoming more attractive again. Emerging markets with strong fiscal positions and high growth, like India, are the primary beneficiaries of this shift. The RBI dividend has essentially signaled to the world that India’s central bank is not only a capable regulator but also a highly profitable institution that supports the sovereign’s goals. This enhances the ‘India Premium’ in global portfolios, potentially leading to a multi-year cycle of capital inflows that could keep the markets in a structural bull phase.
Conclusion: Future Implications and Navigating the Bull Market
The surge to record highs marks a significant chapter in the journey of the Indian stock market, but it also raises questions about what lies ahead. While the RBI’s dividend has provided a powerful short-term boost, the long-term sustainability of this rally will depend on several factors. Investors will be closely watching the upcoming Union Budget, where the government will outline how it intends to utilize the extra funds. A focus on productive capital expenditure rather than populist spending will be key to maintaining the market’s confidence. Additionally, the final outcome of the general elections and the subsequent formation of a stable government will be crucial for policy continuity and investor sentiment.
From a valuation perspective, the market is no longer ‘cheap,’ and many sectors are trading at premiums to their historical averages. This suggests that future gains will have to be backed by actual earnings growth. While the macro-environment is favorable, companies will need to demonstrate that they can translate this growth into better bottom-line results. Global risks also remain on the horizon, including the volatility in crude oil prices and the timing of interest rate cuts by the US Federal Reserve. Any unexpected spike in inflation or a significant slowdown in global growth could act as a drag on the domestic markets.
However, the underlying structural story for India remains incredibly strong. With a healthy banking system, a government with a strong fiscal hand, and a central bank that is effectively managing the currency and liquidity, the foundations for a long-term bull market are firmly in place. Retail participation continues to hit new records, and the institutionalization of the market is reducing the extreme volatility seen in previous decades. For investors, the current record highs are a reminder of the wealth-creation potential of the Indian economy, but they also call for a disciplined approach to portfolio management. As Dalal Street enters this new era of highs, the focus must remain on quality, diversification, and a long-term perspective on the India growth story.
Leave a Reply