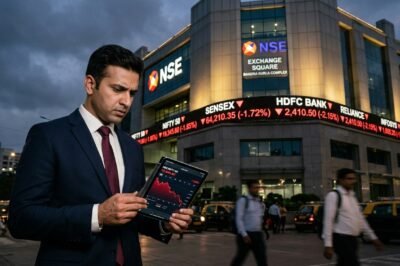
The rhythmic pulse of Dalal Street has taken a somber tone as the Indian equity markets faced another grueling session, ultimately resulting in the Nifty 50 index settling below the psychologically significant 23,350 mark. For seasoned investors and retail participants alike, this breach represents more than just a minor numerical fluctuation; it signals a potential structural shift in the short-term market trend toward a more defensive or even bearish posture. The Sensex, while managing to end only marginally lower compared to its intraday lows, mirrored this pervasive sentiment of exhaustion and uncertainty. The daily volatility has become a hallmark of the current trading environment, leaving many to wonder where the definitive bottom truly lies as support levels continue to crumble. Market participants are currently grappling with a potent cocktail of domestic and international headwinds that have collectively dampened the festive spirit and optimistic projections usually associated with this time of year. As the final closing bell rang, the screens flashed red across major brokerage houses, reinforcing the reality that a significant portion of the post-election rally has been methodically erased by a wave of persistent selling. This analysis delves deep into the mechanics of the current downturn, exploring the technical breakdowns, the massive exodus of foreign capital, and the specific sectors that are bearing the brunt of this pressure.
The Erosion of Market Gains: A Detailed Contextual Analysis
The current downturn in the Indian stock market is not an isolated event but rather the culmination of several weeks of persistent selling pressure, marking one of the most prolonged periods of weakness in recent years. To understand why the Nifty 50 settling below 23,350 is such a significant event, one must look at the historical trajectory of the index over the past six months. Following a period of aggressive expansion fueled by robust corporate earnings and optimistic growth projections, the market entered a phase of extreme overvaluation. Price-to-earnings ratios in several key sectors reached levels that many analysts considered unsustainable. The correction we are witnessing now is, in part, a necessary cooling-off period that allows valuations to align more closely with the actual fundamental growth of companies. However, the speed and intensity of this decline have caught many by surprise, particularly given the strong domestic liquidity that has historically supported the market during such phases.
Furthermore, the narrative of ‘India as an island of growth’ is being tested as global macro factors become increasingly difficult to ignore for local investors. The recent sessions have seen a consistent pattern of ‘sell on rallies,’ suggesting that institutional players are taking every available opportunity to lighten their portfolios and increase cash reserves. This behavioral shift indicates a fundamental lack of confidence in the immediate upside potential, as investors prioritize capital preservation over aggressive growth. The settlement below 23,350 is a technical milestone that validates the bearish outlook held by many technical analysts, effectively turning previous support levels into formidable resistance zones. As we analyze the daily charts, the absence of a strong ‘V-shaped’ recovery highlights the depth of the current skepticism pervading the trading floors of Mumbai and beyond, suggesting that the path to recovery will be a slow, grinding process.
The Technical Breach: Deciphering the Nifty 23,350 Support Level
From a technical standpoint, the level of 23,350 was widely regarded by chartists as a crucial psychological and structural support zone. When an index trades below such a significant mark, it often triggers a cascade of automated selling orders and stop-losses, which further accelerates the downward movement. The Nifty’s inability to hold this level suggests that the bears have gained firm control over the market narrative. Technical indicators such as the Relative Strength Index (RSI) are hovering in the oversold territory, yet the lack of a meaningful bounce suggests that the momentum is still skewed heavily to the downside. Analysts are now closely watching the 200-day Simple Moving Average (SMA), which often serves as the last line of defense for a long-term bull market. A sustained trade below this average could signal a transition from a healthy correction into a more prolonged bear phase, necessitating a complete re-evaluation of investment strategies.
Moreover, the formation of ‘lower highs and lower lows’ on the daily and weekly timeframes is a classic sign of an established downtrend. Every attempt by the bulls to reclaim the 23,500-23,600 range in recent days has been met with aggressive selling by Foreign Portfolio Investors (FPIs). This technical gridlock has created a frustrating environment for retail traders who have been conditioned over the last three years to ‘buy the dip.’ The current market structure suggests that the ‘dip’ is becoming a deeper ‘trench,’ necessitating a change in strategy from aggressive buying to a more cautious, wait-and-watch approach. The volume profiles during these down days have also been relatively high, indicating that the selling is not just a result of low liquidity but a deliberate and massive exit by large-scale institutional participants who are reallocating their capital to other markets.
The Foreign Capital Exodus: Understanding the FPI Sell-off Dynamics
One of the most significant and immediate contributors to the current market malaise is the relentless selling by Foreign Portfolio Investors. In the current month alone, the quantum of outflows has been staggering, reaching levels that rival previous global financial crises. There are several reasons for this sudden and dramatic shift in sentiment among global fund managers toward Indian equities. Firstly, the strengthening of the US Dollar Index (DXY) has made emerging market assets inherently less attractive. As the Greenback gains strength on the back of resilient US economic data, the carry trade becomes less profitable, prompting funds to move capital back to the safety of US Treasuries and dollar-denominated assets. This is a classic ‘risk-off’ move that typically hits emerging markets like India the hardest, regardless of their individual domestic economic strength.
Secondly, the rising yields on US 10-year Treasury bonds have provided a compelling and lower-risk alternative to the volatile equity markets. When global investors can get a guaranteed return of over 4.4% in a risk-free asset, the premium required to hold Indian equities increases significantly. This has led to a systematic reallocation of global portfolios away from high-beta emerging markets. Furthermore, the ‘China Factor’ cannot be ignored. With the Chinese government recently announcing various stimulus measures to revive its sluggish economy, some global capital is being diverted from the relatively expensive Indian market to the cheaper, undervalued Chinese stocks. This rotation of funds has created a liquidity vacuum in the Indian large-cap space, particularly in high-weightage stocks within the Nifty 50, which are the primary targets of FPI selling due to their high liquidity.
Sectoral Performance: Winners and Losers in a Volatile Session
A granular look at sectoral performance during this period of volatility reveals a stark divergence between various industries. The banking and financial services sector, which carries the highest weightage in the Nifty, has been under significant pressure. Concerns over narrowing Net Interest Margins (NIMs) and a potential slowdown in credit growth have weighed heavily on private sector banks. Even the stalwarts of the industry have seen their share prices erode, contributing heavily to the overall index decline. On the other hand, the IT sector has shown bouts of resilience, albeit amidst high volatility. The outlook for IT remains clouded by the ‘Trump Trade’—uncertainty regarding H-1B visas and outsourcing policies under a new US administration—but some investors view these stocks as a natural hedge against a weakening Rupee.
The automotive sector is another area of concern, as recent data suggests a slowdown in urban demand and rising inventory levels at dealerships across the country. Despite the festive season, the sales figures have not lived up to the lofty expectations set by the market earlier in the year, leading to a de-rating of several major auto stocks. Conversely, defensive sectors like FMCG and Pharma have provided some modicum of stability, though even they are not entirely immune to the broader market sentiment. In times of high uncertainty, investors typically flock to companies with stable cash flows and inelastic demand for their products. However, the ‘sell everything’ mentality that occasionally takes over during periods of panic has meant that even these safe havens have seen their valuations compressed as part of the wider market deleveraging process.
Macroeconomic Headwinds: Inflation and the RBI’s Strategic Stance
The domestic macroeconomic environment has also added a layer of complexity to the list of worries for equity investors. The recent spike in retail inflation, primarily driven by rising food prices and supply-side disruptions, has dampened hopes for an imminent interest rate cut by the Reserve Bank of India (RBI). The central bank’s primary mandate is price stability, and as long as inflation remains above the comfort zone of 4%, the possibility of a pivot in monetary policy remains slim. High interest rates are generally negative for equities as they increase the cost of capital for companies and reduce the disposable income of consumers, thereby impacting corporate earnings. The ‘higher-for-longer’ interest rate narrative is now being priced into the market, leading to a downward revision of earnings estimates for the upcoming quarters.
Furthermore, the depreciation of the Indian Rupee against the US Dollar has reached record lows, creating another layer of complexity for the central bank and the government. While a weaker Rupee benefits exporters, it significantly increases the cost of imports, particularly crude oil, which India imports in massive quantities. This ‘imported inflation’ can have a cascading effect on the entire economy, from logistics costs to manufacturing margins. The RBI has been intervening in the forex market to prevent a volatile and disorderly slide in the currency, but this also drains foreign exchange reserves and tightens domestic liquidity. The synergy of rising inflation, a weakening currency, and stagnant industrial production has created a challenging backdrop for the equity markets, making it difficult for the Nifty to maintain its upward trajectory without a significant improvement in these fundamental indicators.
Future Implications: Navigating the Path to Market Stabilization
Looking ahead, the road to recovery for the Indian stock market appears to be a gradual and cautious process rather than a swift, aggressive rebound. The first sign of stabilization will likely come from a noticeable slowdown in FPI selling. Until the global macro environment—specifically US bond yields and the dollar index—reaches a state of equilibrium, the pressure on emerging market equities is expected to persist in the medium term. Investors should also keep a close eye on the remaining corporate earnings reports, as any positive surprises in guidance or margins could provide the necessary catalyst for a dead-cat bounce or a more sustainable recovery. The level of 23,000 is now being cited by many analysts as the next major psychological support for the Nifty 50, and a successful defense of this level could signal the formation of a long-term base.
For long-term investors, this period of volatility presents a unique opportunity to accumulate high-quality stocks at much more reasonable valuations than those seen just three months ago. The structural growth story of India remains largely intact, driven by young demographics, increasing digitalization, and massive infrastructure development projects. However, the short-term focus for participants must remain on risk management and portfolio diversification. The era of easy money and one-way rallies seems to have paused for the time being, giving way to a ‘stock picker’s market’ where fundamental analysis, earnings visibility, and patience will be highly rewarded. As the market digests the current set of challenges, the focus will eventually shift back to the long-term potential of the Indian economy, but for the immediate future, the mantra on Dalal Street is one of extreme caution and vigilance as the Nifty settles into its new, lower trading range.
Leave a Reply